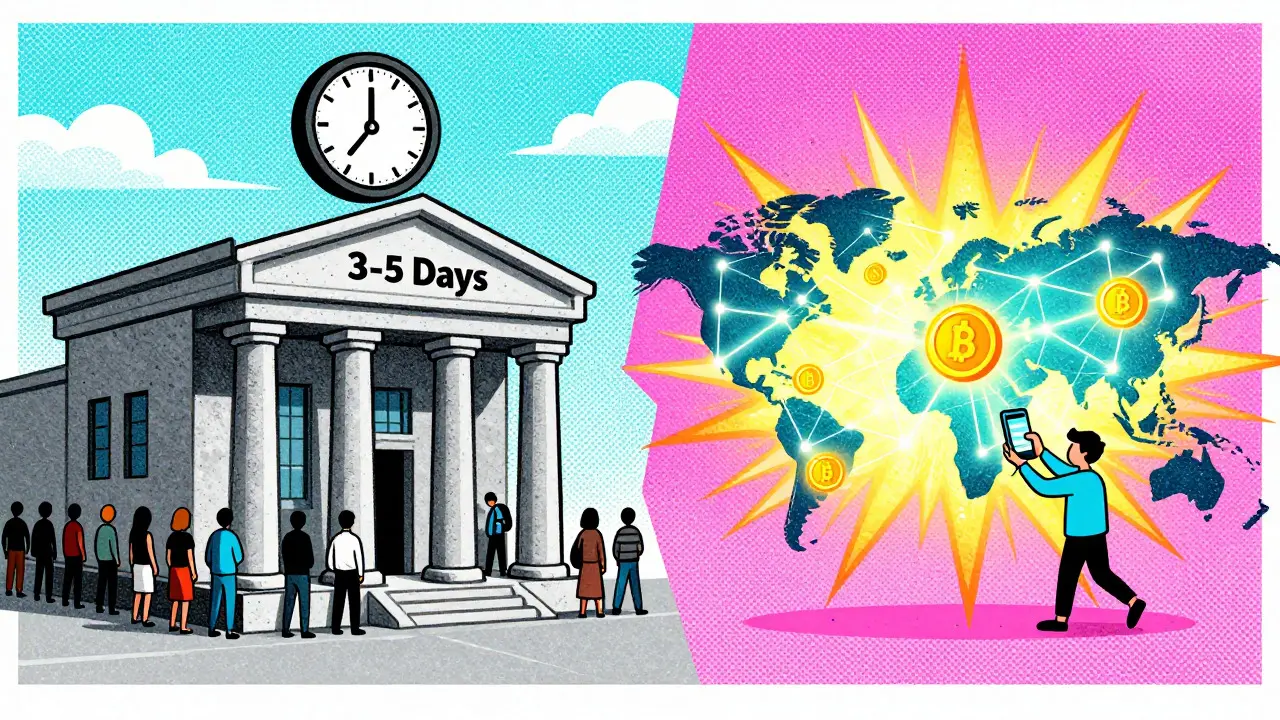
Imagine sending money to a relative in another country. With a traditional bank, you might wait three to five business days and pay a fee of $25 or more. With Decentralized Finance is a blockchain-based financial ecosystem that allows peer-to-peer transactions without intermediaries, the same transfer can settle in seconds for a fraction of the cost. This stark difference highlights why millions are shifting their attention toward digital assets. However, jumping into crypto isn't just about speed; it involves a fundamental change in how you manage risk, privacy, and ownership. As of mid-2025, DeFi holds over $247 billion in Total Value Locked, while major U.S. banks still control nearly $20 trillion in assets. Both systems have massive followings, but they serve different needs and come with distinct trade-offs.
Key Takeaways
- Speed and Cost: DeFi transactions settle in seconds to minutes with lower fees, whereas traditional banking often takes days and charges higher fixed fees.
- Control vs. Safety: DeFi offers self-custody (you hold the keys) but lacks deposit insurance; traditional banks offer FDIC protection up to $250,000 but control your funds.
- Yields: DeFi protocols like Aave offer significantly higher interest rates (often 8-12% APY) compared to traditional savings accounts averaging 0.45% APY.
- Accessibility: DeFi requires only an internet connection and a wallet, making it accessible to the unbanked, while traditional banking requires strict KYC documentation.
- Risk Profile: DeFi carries smart contract risks and volatility; traditional banking faces institutional fraud risks but has legal recourse.
The Core Architectural Difference
To understand the comparison, you first need to look at the engine under the hood. Traditional banking relies on centralized databases maintained by financial institutions. When you deposit money, the bank records it in its internal ledger. You trust the institution to keep your data safe and your money available. In contrast, DeFi operates on public blockchains like Ethereum, Polygon, or Solana. Here, Smart Contracts are self-executing programs stored on a blockchain that automatically enforce terms when conditions are met. These contracts replace the need for a middleman. If you lend USDC on a platform like Compound, the smart contract handles the loan, calculates interest, and manages repayment without a human employee touching your file. This shift from 'trust me' to 'verify it yourself' is the philosophical heart of the debate.
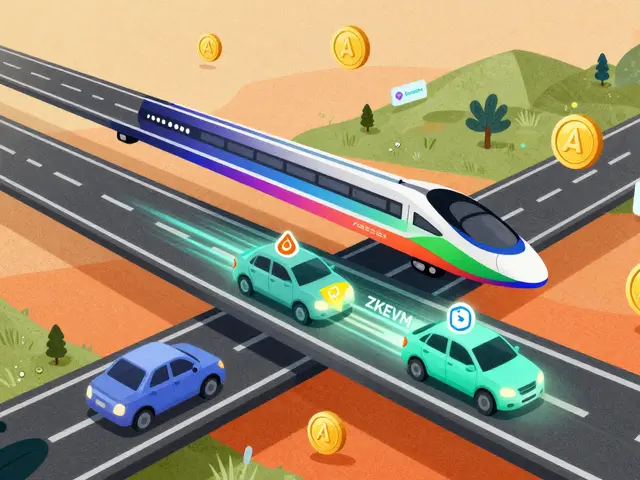
This architectural choice impacts everything from transaction speed to transparency. On Ethereum, a transaction typically settles in about 15 seconds. On faster chains like Solana, it’s under half a second. Traditional wire transfers, especially cross-border ones, rely on the SWIFT network, which often takes 72 to 120 hours to clear. For someone running a small business or managing international payroll, this delay can be painful. But there is a catch: DeFi transparency means every transaction is public. While this creates an audit trail that traditional banks envy, it also means your pseudonymous address is visible to anyone who looks. Traditional banking offers privacy through opaque ledgers, though this comes with the requirement to pass Know Your Customer (KYC) checks.
Costs, Fees, and Yields
Let’s talk numbers, because that’s usually what drives the decision. Traditional banking fees are layered and often hidden. You might face monthly maintenance fees averaging $12.50, ATM withdrawal fees of $2-$3, and wire transfer fees ranging from $25 to $30. International wires can eat up 5-7% of your total amount. DeFi fees are primarily 'gas fees,' which pay for computation on the network. During normal congestion in Q2 2025, Ethereum gas averaged around $3.50 per transaction, while Layer 2 solutions like Polygon dropped this to roughly $1.20. After recent upgrades, some Layer 2 costs have dipped as low as $0.15. It’s not zero, but it’s predictable and generally lower than bank overheads.
The real magnet for DeFi users is yield. Traditional savings accounts in the U.S. averaged a mere 0.45% Annual Percentage Yield (APY) in Q2 2025. That’s barely keeping pace with inflation. In DeFi, lending stablecoins like USDC on platforms such as Aave or Compound can yield between 8% and 12% APY. Why the gap? Because DeFi markets are global and competitive, driving prices down for borrowers and yields up for lenders. However, these yields aren’t guaranteed. They fluctuate based on demand. If fewer people want to borrow, your rate drops. Traditional bank rates are set by central banks and institutional policies, offering stability at the cost of lower returns.
| Feature | DeFi | Traditional Banking |
|---|---|---|
| Avg. Transaction Speed | Seconds to Minutes | Hours to Days |
| Cross-Border Transfer Time | 3-5 Seconds (Stellar) | 3-5 Business Days |
| Typical Fees | $0.15 - $3.50 (Gas) | $12.50/mo + $25/wire |
| Avg. Savings Yield (2025) | 8.7% APY (Aave USDC) | 0.45% APY |
| Security Model | Cryptographic / Smart Contract | Institutional / FDIC Insurance |
| Onboarding Requirement | Internet + Wallet | ID, Address Proof, KYC |
Risk Management: Who Protects Your Money?
This is where the conversation gets serious. In traditional banking, if your bank fails, the Federal Deposit Insurance Corporation (FDIC) protects your deposits up to $250,000 per depositor. If a hacker steals from your account due to bank negligence, you have legal recourse and chargebacks. In DeFi, you are your own bank. If you lose your private key, your money is gone forever. There is no customer support line to call. If a smart contract has a bug, hackers can exploit it. The Poly Network hack in 2021 resulted in a loss of $610 million. While many DeFi hacks are mitigated quickly due to community alerts, the risk remains entirely on the user. According to Hedera’s 2025 analysis, 97% of DeFi fraud victims receive no restitution, compared to a high resolution rate for traditional account takeovers.
However, traditional banking isn’t risk-free. Inflation erodes purchasing power, and regulatory changes can freeze assets or impose capital controls. DeFi offers censorship resistance. No government can easily freeze your funds unless they target your specific wallet address directly, which is technically difficult on decentralized networks. For users in countries with unstable currencies or restrictive banking laws, DeFi provides a lifeline. It’s a trade-off: accept the technical risk and lack of insurance for the sake of autonomy and higher yields, or accept lower returns and less control for the safety net of institutional backing.
Accessibility and User Experience
Getting started with traditional banking is straightforward for most people in developed economies. You walk into a branch or use an app, show your ID, and open an account in about 15 minutes. J.D. Power surveys confirm this ease of access. DeFi, however, has a steeper learning curve. You need to buy cryptocurrency, set up a non-custodial wallet like MetaMask or Trust Wallet, and understand concepts like gas fees, slippage, and seed phrases. Openware’s 2025 study found that 68% of new users need two to three weeks to feel comfortable using DeFi apps. The documentation for protocols like Aave scores well with developers but often confuses beginners.
Despite the complexity, DeFi solves a massive problem: exclusion. The World Bank reports that 5.4 billion people globally are unbanked or underbanked. Traditional banks require proof of address, steady income, and clean credit histories. DeFi requires only an internet connection. A farmer in Bihar, India, shared his experience on Reddit, noting he earned 12.3% APY on Aave with zero paperwork, something impossible with local banks requiring land documents he didn’t have. Similarly, a user in Nairobi accessed 9.1% APY stablecoin yields in 20 minutes using a smartphone, bypassing months of pay stub requirements. For the underserved, DeFi isn’t just a tech toy; it’s a gateway to financial participation.
The Future: Convergence and Regulation
It’s not strictly 'us versus them.' The lines are blurring. Traditional giants are adopting blockchain technology. JPMorgan’s Onyx platform processed $1.2 trillion in blockchain transactions in 2024, showing that big banks see value in the underlying tech even if they don’t embrace full decentralization. Meanwhile, regulators are catching up. The U.S. Office of the Comptroller of the Currency approved 17 national banks for cryptocurrency custody as of July 2025. This move legitimizes crypto storage within the regulated system. On the DeFi side, Ethereum’s Dencun upgrade reduced Layer 2 costs by 90%, making the technology more usable for the average person.
Experts predict a hybrid future. Goldman Sachs suggests DeFi will capture 15-20% of traditional banking functions by 2030, particularly in cross-border payments and yield generation. Demographics play a huge role here. 57% of Millennials and Gen Z now prefer DeFi apps over mobile banking platforms, driven by transparency and higher yields. Yet, trust remains a barrier. 63% of DeFi users couldn’t explain smart contract risks in a recent European Central Bank report. As education improves and regulations clarify, we may see a world where you use a bank app for your salary and emergency fund, but use DeFi protocols for investing, trading, and international transfers. The best approach might not be choosing one, but knowing which tool fits which job.
Frequently Asked Questions
Is DeFi safer than traditional banking?
It depends on the type of risk. Traditional banking is safer against theft and bank failure due to FDIC insurance and legal recourse. DeFi is safer against censorship and currency devaluation but carries higher risks from smart contract bugs, private key loss, and market volatility. For most users, a mix of both offers the best balance.
How much money do I need to start with DeFi?
There are no minimum deposits in DeFi. You can start with as little as $10 or $20, provided you have enough to cover initial gas fees. However, to make meaningful yields, you generally need a larger principal. Always keep a small amount of ETH or SOL for gas fees separate from your investment capital.
What happens if I lose my DeFi wallet password?
If you lose your 'seed phrase' (the 12 or 24 words that act as your master key), you lose access to your funds permanently. Unlike a bank, there is no 'forgot password' button. This is why writing down your seed phrase on paper and storing it securely is the single most important security practice in DeFi.
Are DeFi yields taxed differently than bank interest?
In many jurisdictions, yes. Interest earned in DeFi is often treated as ordinary income, similar to bank interest. However, swapping tokens or moving assets between chains can trigger taxable events. Keep detailed records of every transaction, as tax reporting for crypto is complex and varies by country.
Which is better for international money transfers?
For speed and cost, DeFi is generally superior. Transfers via stablecoins on fast chains can cost cents and arrive instantly. Traditional banks often charge 3-5% and take several days. However, if the recipient prefers receiving fiat currency directly in a bank account, you may still need a conversion step, which adds friction.
Bill Patterson
August 25, 2026 AT 22:22another long winded piece of fluff trying to sell you a dream 🙄
Matt Reckdenwald
August 26, 2026 AT 11:05You really know how to make people feel like they are missing out on the most exciting financial revolution in human history, don't you? It is almost as if you are standing at the edge of a vast, shimmering ocean of opportunity and telling everyone that the water is too cold to wade in. The way you dismiss the potential here feels like watching someone ignore a rainbow because it might rain later. We are talking about freedom, Bill, pure unadulterated sovereignty over our own assets! Why do you always have to be so gloomy about progress? It is like complaining that the sun is too bright when you are wearing sunglasses made of lead. The world is changing, and those who refuse to see it will be left standing in the shadows while the rest of us dance in the light of decentralization. Your skepticism is just fear dressed up in a cheap suit. Embrace the chaos, embrace the code, and stop hiding behind your old-world fears. The future is now, and it is glowing with neon possibilities that you simply cannot perceive from your little bunker of doubt.
Melanie Armijo
August 28, 2026 AT 01:28It's funny how we spend so much time debating which container holds the water, when we should be asking why we are thirsty in the first place. Perhaps the real issue isn't DeFi versus banks, but the fundamental human desire for security in an uncertain universe. We build walls, whether they are made of brick or blockchain, to keep the monsters out. But what if the monster is inside us? The anxiety of loss is a universal language, spoken by the banker and the crypto trader alike. Maybe the answer isn't choosing a side, but accepting that all structures are temporary and impermanent. We cling to these systems because they give us a sense of control, a false comfort in the face of entropy. In the end, both the bank vault and the hardware wallet are just metaphors for our fear of letting go. So perhaps the wisest thing is to hold nothing tightly, to flow with the currents of change rather than fighting them. What do you think, is it the money that matters, or the peace of mind that comes from knowing you can lose it all?
Laine Van Sickle
August 28, 2026 AT 16:01i dont get why ppl hate defi so much its literally free money if u play ur cards right 😒 also banks r basically stealing from u with those fees its so rude honestly
Rajni Mathur
August 28, 2026 AT 21:19While your enthusiasm is palpable, one must consider the regulatory labyrinth that awaits the unwary traveler. The notion of 'free money' is a dangerous simplification that ignores the complex interplay of tax liabilities, smart contract vulnerabilities, and market volatility. Have you considered the implications of losing custody of your assets without recourse? The traditional banking system, for all its perceived slowness, offers a safety net woven from decades of legal precedent and institutional stability. To dismiss this structure as mere 'rudeness' is to overlook the intricate machinery that keeps the global economy afloat. Furthermore, the environmental cost of proof-of-work mechanisms, though diminishing, remains a point of contention among informed stakeholders. One must weigh the allure of high yields against the very real risk of total capital loss due to technical failure or regulatory crackdowns. The path forward requires not blind faith in technology, but a nuanced understanding of both paradigms. Perhaps a hybrid approach, where one utilizes DeFi for specific transactions while maintaining core savings in insured accounts, would offer a more balanced perspective. The data suggests that diversification, not dogma, is the key to long-term financial health. Let us not forget that innovation without regulation often leads to systemic instability, as seen in previous financial bubbles. Therefore, caution is not cynicism; it is prudence. The journey into decentralized finance is a marathon, not a sprint, and requires careful navigation of both technological and legal terrains. Do not let the excitement cloud your judgment regarding the foundational principles of asset preservation. A well-informed investor understands that risk and reward are two sides of the same coin, and flipping it too carelessly can result in a painful landing. Consider the long-term horizon before making impulsive moves based on short-term gains. The market rewards patience and research, not haste and hype. Let your decisions be guided by analysis, not emotion. The future of finance is indeed digital, but it must be built on a solid foundation of trust and transparency. Until then, tread carefully and keep your eyes open for the hidden pitfalls that lie beneath the surface of every shiny new platform. This is not a criticism of your choice, but a reminder that wisdom lies in balance. May your investments be fruitful and your risks manageable. The road ahead is long, but with the right mindset, you can navigate it successfully. Keep learning and stay vigilant. The best strategy is often the one that protects your downside while allowing for upside potential. Do not underestimate the power of compound interest, whether in a bank account or a DeFi protocol. Time is your greatest ally, but only if you use it wisely. Stay focused on your goals and let the noise fade into the background. Success in finance is a marathon, not a sprint, and consistency is key. Remember that every great empire was built on a strong foundation, and your financial empire is no different. Lay the bricks carefully and ensure they are set in concrete. The view from the top is worth the effort, but only if the structure can withstand the winds of change. Here's to your continued success and prudent decision-making. May the odds be ever in your favor. 📈💼
Ashwin Bhandurge
August 30, 2026 AT 09:09Great points everyone! 💪 The key is finding the right balance. I started small with $50 on Polygon and learned fast. Don't be afraid to start small and scale up. You got this! 🔥