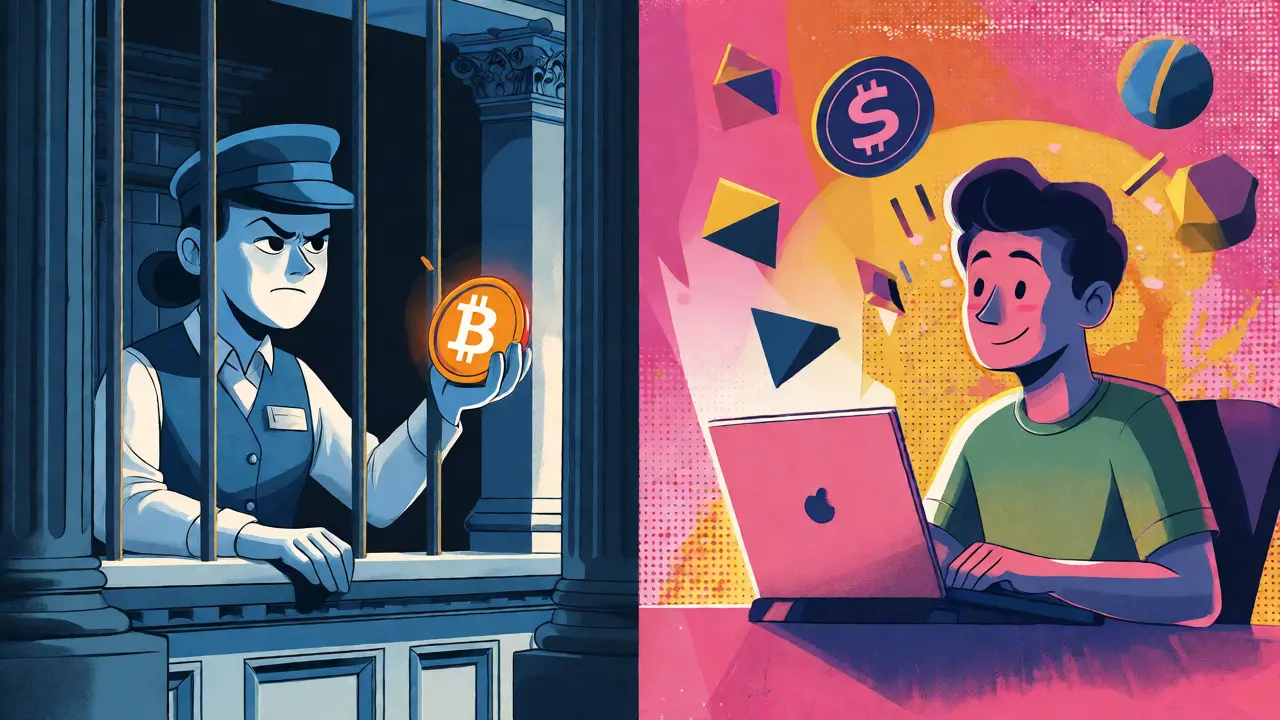
Imagine walking into a bank in Buenos Aires with a stack of pesos and asking to buy Bitcoin. You’d likely get a polite but firm "no." This isn’t because the teller doesn’t understand crypto-it’s because Banco Central de la República Argentina (BCRA) explicitly banned traditional banks from facilitating cryptocurrency transactions. As of late 2025, this restriction remains one of the most distinct features of Argentina’s financial landscape. While the country has aggressively liberalized its currency controls and embraced blockchain technology, it has drawn a hard line between traditional banking and the digital asset ecosystem.
This creates a unique paradox for investors and everyday users. On one hand, Argentina is one of the most crypto-friendly nations in Latin America, with roughly 30% of the population owning digital assets. On the other, you cannot use your local bank account to directly trade these assets. Instead, you must navigate a parallel system of licensed entities known as Virtual Asset Service Providers (VASPs). If you’re planning to invest, trade, or simply hold crypto in Argentina, understanding this separation is critical. It dictates where your money goes, how you pay taxes, and which platforms are actually legal to use.
The Core Rule: Banks Are Out, VASPs Are In
The central pillar of Argentina’s current regulatory stance is the strict segregation of duties. The BCRA prohibits commercial banks from offering any crypto-related services. This includes custody, trading, exchange, and even holding stablecoins like USDT or USDC within a standard checking or savings account. The rationale is straightforward: the central bank wants to protect foreign exchange reserves and maintain control over monetary policy without the volatility of crypto bleeding into the traditional banking sector.
So, who handles the transactions? Enter the Virtual Asset Service Provider (VASP). A VASP is defined under Law 27,739 as an entity that provides services related to virtual assets, such as exchanging fiat for crypto, transferring assets, or providing custodial wallets. These providers are not banks; they are specialized financial institutions regulated by the National Securities Commission (CNV), not the BCRA.
This distinction matters because it changes the compliance burden. Banks answer to the central bank regarding liquidity and reserve requirements. VASPs answer to the CNV regarding market conduct, anti-money laundering (AML) standards, and consumer protection. For the user, this means your crypto wallet is technically separate from your bank account. To move money from your bank to your crypto portfolio, you aren’t just making a transfer; you’re moving funds between two different regulatory jurisdictions.
Law 27,739 and the Rise of Regulated VASPs
The framework governing this split was solidified with Law 27,739, enacted in March 2024. This legislation marked Argentina’s first comprehensive attempt to regulate the crypto industry. Before this, the space was largely a gray area-popular but legally ambiguous. The new law granted the CNV oversight powers over all VASPs operating in the country, effectively bringing them under the same umbrella as stock brokers and investment funds.
To operate legally, every VASP had to register with the CNV by specific deadlines outlined in Resolution 1058/2025. The timeline was tight:
- July 1, 2025: Individual operators had to register.
- August 1, 2025: Argentine-incorporated companies were required to be fully compliant.
- September 1, 2025: Foreign entities targeting Argentine users had to finalize their registration.
These deadlines weren’t just bureaucratic hurdles. They came with strict operational requirements. VASPs must prove they have sufficient net worth in USD, adhere to FATF-recommended AML/CFT (Counter-Terrorist Financing) standards, and implement robust Know Your Customer (KYC) procedures. If a platform hasn’t registered with the CNV, it’s operating illegally. Using an unregistered platform now carries significant risk, including potential freezes on funds or tax complications.
Stablecoins and the End of the Cepo Cambiario
You might wonder why banks would ban crypto if Argentinians rely so heavily on stablecoins. In a country with high inflation, the US Dollar is king, and USDT/USDC often serve as digital dollars. The key development in April 2025 changed the game: the government lifted most of the "cepo cambiario" (currency controls). Previously, buying physical US dollars was restricted and expensive due to multiple exchange rates. Now, individuals can buy dollars freely.
However, lifting currency controls did not lift the banking ban on crypto. You can still buy dollars at the bank, but you cannot buy Bitcoin at the bank. This forces users to adopt a hybrid workflow. Typically, an investor will withdraw pesos from their bank account, send them to a registered VASP via wire transfer or PSE (electronic payment system), and then execute the trade on the VASP’s platform. This extra step adds friction but ensures compliance.
For businesses, this separation complicates accounting. Since banks don’t process crypto transactions, reconciling statements requires matching bank transfers with VASP transaction logs. The Financial Intelligence Unit (UIF) enforces strict reporting rules here. VASPs must report suspicious activities within 150 days and provide monthly reports detailing client numbers, traded volume, and top assets. This data flows to regulators, creating a transparent trail that didn’t exist in the early days of crypto adoption.
Tax Implications and the Blanqueo Program
Regulation brings taxes. Under Law 27,743, crypto holdings are subject to taxation, and the government launched a "blanqueo" (asset regularization) program to encourage citizens to declare their digital wealth. The window for this regularization remained open until September 30, 2025. Failure to declare crypto holdings could result in penalties, especially since the UIF and AFIP (the federal tax agency) are increasingly cross-referencing VASP data with tax returns.
Cross-border transactions also face scrutiny. Transfers involving crypto across borders are subject to taxes ranging from 5% to 15%, aimed at boosting transparency and managing capital flight. Because these transactions bypass the traditional banking SWIFT network, they are tracked through the VASP’s compliance systems rather than bank ledgers. This means the government sees your crypto movements even if your bank statement only shows a generic transfer to a tech company.
| Feature | Traditional Bank | Registered VASP |
|---|---|---|
| Crypto Trading | Prohibited | Allowed & Regulated |
| Fiat Deposits | Standard Checking/Savings | Via Wire/PSE Transfer |
| Regulator | BCRA | CNV |
| Stablecoin Custody | Not Available | Available (if licensed) |
| AML Reporting | Bank Secrecy Laws apply | Direct UIF Reporting |
Impact on Travelers and Digital Nomads
If you’re a tourist or a digital nomad visiting Argentina, these restrictions affect how you spend your money. You can’t walk into a Banco Nación branch and ask them to convert your Bitcoin into pesos. You need a registered VASP with a local presence or an international platform that accepts Argentine users under the new licensing regime.
Many international exchanges have adapted by partnering with local VASPs or obtaining their own licenses. However, smaller or unlicensed platforms may block Argentine IP addresses to avoid compliance costs. Always check if the platform displays its CNV registration number before depositing funds. If you’re using crypto to pay for hotels or tours, ensure the merchant accepts direct peer-to-peer transfers, as they likely cannot accept credit card payments processed through banks that refuse crypto-linked charges.
Future Outlook: Innovation vs. Stability
Is this separation sustainable? Critics argue that banning banks from crypto stifles innovation. Small startups struggle to access traditional banking services for their operational needs while competing against larger, well-capitalized VASPs. There’s no integrated solution where you can see your Bitcoin balance next to your peso balance in a single app provided by your main bank.
Yet, the government seems committed to this model. By keeping crypto out of the banking system, they insulate the economy from crypto crashes while still allowing the sector to grow. Recent moves, such as General Resolution No. 1069/2025, show the CNV is expanding its reach to tokenized real-world assets (RWA). This suggests that while banks stay out, the securities market is embracing blockchain. The future of Argentine finance isn’t a merger of banks and crypto; it’s a coexistence of two distinct, highly regulated ecosystems.
For now, if you want to participate in Argentina’s vibrant crypto scene, you must leave the bank behind. Find a CNV-registered VASP, complete your KYC, and keep meticulous records. The days of wild-west trading are over, replaced by a structured, albeit segregated, financial environment.
Can I buy Bitcoin with my Argentine bank account?
No, you cannot buy Bitcoin directly through your Argentine bank account. The BCRA prohibits banks from facilitating crypto purchases. You must transfer pesos from your bank to a registered VASP and purchase the crypto there.
What happens if I use an unregistered crypto platform?
Using an unregistered platform risks having your funds frozen or facing legal issues. The CNV mandates registration for all VASPs serving Argentine users. Unregistered platforms may also fail to comply with AML laws, leading to potential tax audits.
Are stablecoins banned in Argentine banks?
Yes, banks cannot offer custody or trading services for stablecoins like USDT or USDC. You must hold these assets through a licensed VASP or a self-custody wallet, not in a traditional bank account.
Do I need to pay taxes on crypto profits in Argentina?
Yes, crypto profits are taxable. Additionally, you must declare your holdings under the 'blanqueo' program if applicable. Cross-border crypto transactions may incur additional taxes between 5% and 15% depending on the nature of the transfer.
Who regulates crypto exchanges in Argentina?
The National Securities Commission (CNV) regulates crypto exchanges and VASPs. The BCRA regulates banks but does not oversee crypto operations, maintaining a strict separation between the two sectors.